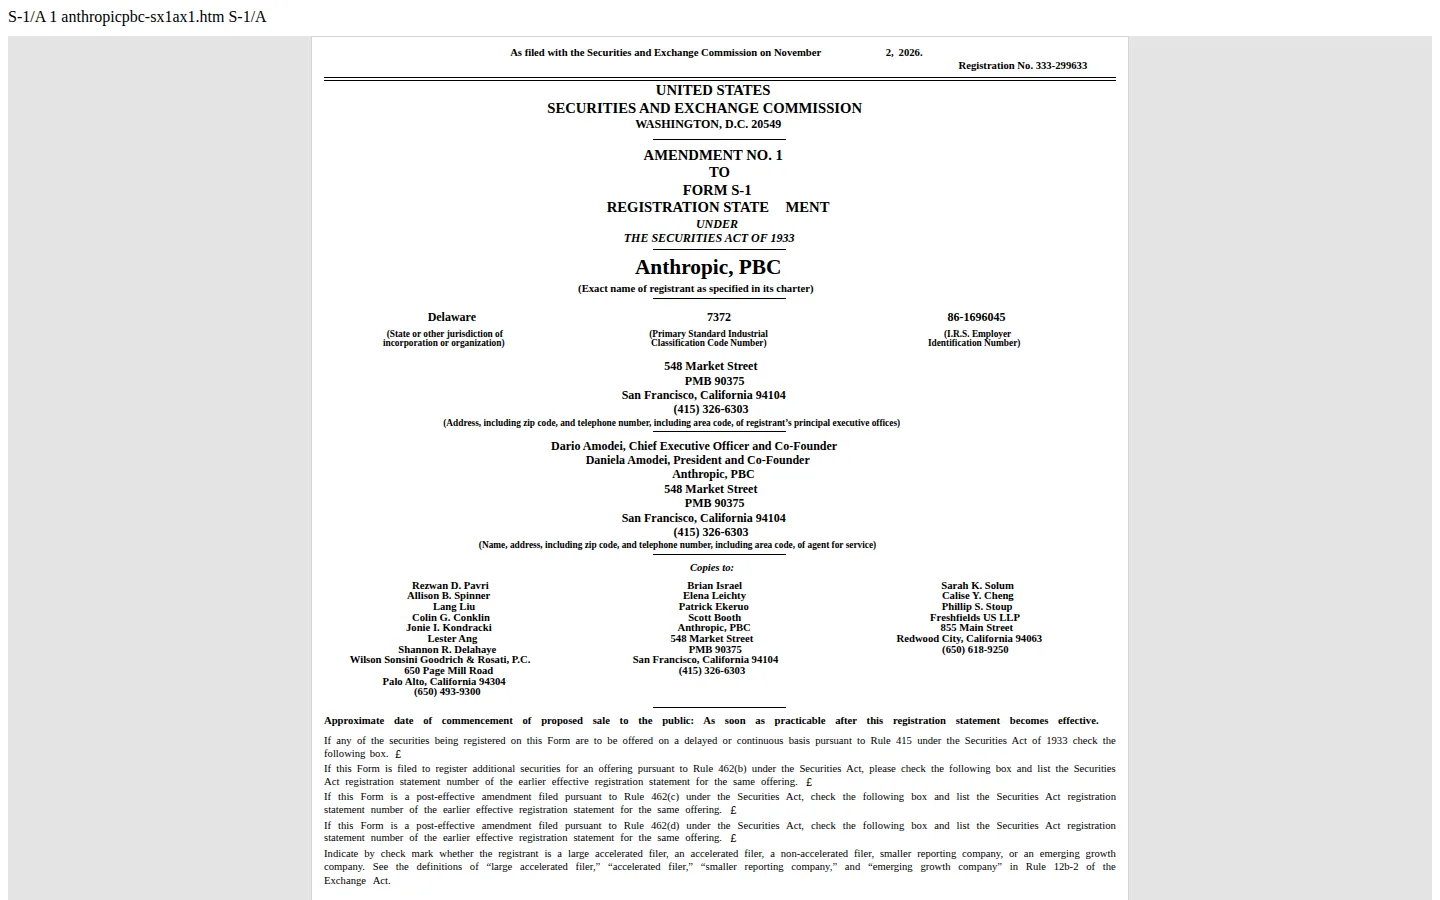
Anthropic amended its IPO registration statement on November 2, 2026, and the amendment carries the quarter the first filing left out. Revenue for the three months ended September 30, 2026 came in at $16,956 million, against $1,382 million a year earlier, a 1,127% increase on the company’s own count. The same quarter produced a $567 million operating loss and a $23,291 million net loss.
What was actually released
No model, no price change, no feature. This is Amendment No. 1 to Form S-1, registration number 333-299633, filed with the Securities and Exchange Commission on November 2, 2026. It restates the whole prospectus with three more months of accounts and adds a quarterly breakdown that runs back to March 2025.
The listing target is unchanged: Class A common stock on Nasdaq under the symbol ANT. The date sits on the cover, above two fields that are still blank, the price range and the share count. The raise has no size, so no valuation follows from the document.
The September quarter, on the filing’s own lines
- Revenue of $16,956 million, twelve times the $1,382 million of the September quarter of 2025.
- Operating loss of $567 million, after operating income of $974 million in the June quarter.
- Net loss of $23,291 million, of which $21,936 million is a non-cash mark on convertible notes.
What the claim rests on
The loss headline is the least informative number in the amendment. It is also the only one that survives a summary, so the quarterly table is worth reading before the totals.
| Quarter | Revenue | Compute and infrastructure | Operating income (loss) | Net loss |
|---|---|---|---|---|
| Q3 2025 | $1,382M | $2,047M | minus $3,089M | minus $12,138M |
| Q4 2025 | $2,040M | $2,945M | minus $2,836M | minus $16,858M |
| Q1 2026 | $4,731M | $3,387M | minus $1,667M | minus $14,439M |
| Q2 2026 | $11,555M | $5,558M | $974M | minus $66,309M |
| Q3 2026 | $16,956M | $9,863M | minus $567M | minus $23,291M |
Revenue grew 12.3 times in four quarters. Compute and infrastructure grew 4.8 times over the same span, which is the case for a frontier lab as a business: the compute bill grows far more slowly than the revenue it serves. The company puts the same shift at 1,127% revenue growth against 382% compute growth for the September quarter alone.
That ratio moved the wrong way in the last three months. Compute fell to 48% of revenue in the June quarter and rose to 58% in September, and the filing names the reason: $5.0 billion of compute bought through short-term commitments, which it says “currently costs significantly more than comparable compute procured under our multi-year commitments”. Add $2.0 billion of non-cash donation matching charges and the operating result flipped from a $974 million profit to a $567 million loss.
Because we typically procure compute 12 to 18 months in advance of availability, these expenses are generally fixed in the near term and increase as committed compute becomes available to us.
The net loss is a different animal. Most of it is the accounting treatment of instruments that convert into equity when the company lists, and the filing gives the bridge line by line.
| Q3 2026 line | Amount |
|---|---|
| Net loss | minus $23,291M |
| Change in fair value of convertible notes and related instruments | $21,936M |
| Non-cash donation matching charges | $1,960M |
| Stock-based compensation | $1,070M |
| Mark-to-market instruments | $1,557M |
| Tax effects | minus $65M |
| Adjusted net income, company definition | $3,167M |
On Anthropic’s own adjusted measure the quarter made $3,167 million, against a $1,168 million loss a year earlier. Adjusted operating income rose to $2.5 billion, with the margin down from 19% to 15% because of the spot compute. Both figures are the company’s, not ours, and both exclude costs a shareholder still carries.
What is not accounting is the commitment book. Anthropic reports $895.4 billion of purchase commitments and leases, substantially all of it compute and infrastructure, with $447.5 billion due before the end of 2030 and $69.8 billion inside the twelve months after September 30, 2026. Against that it holds $95.6 billion of cash and $36.3 billion of short-term investments.
What the amendment does not say
- No price range and no share count. Both cover fields are blank, so the valuation the offering implies cannot be computed.
- No number for the premium on short-term compute. The filing says “significantly more” and leaves the gap unquantified.
- No gross margin line for the quarter. In 2025 the company moved from presenting cost of revenue, gross profit and the usual functional lines to reporting expenses by nature, so compute and infrastructure now sits inside operating expenses.
On this page
What it changes for teams buying Claude
Three things here land on a tool budget.
Capacity, not list price, is the constraint. When $5.0 billion of a quarter’s compute has to be bought late at a premium, the pressure shows up as rate limits, deprecations and model retirements before it shows up as a price increase, because the price curve has moved the other way. Anthropic says Opus 5.5 cut cost per task by about 40% against Opus 5.
The price cuts are large enough to appear in the accounts. For the September quarter, about $600 million of revenue was given up to price reductions introduced with new model versions and contractual discounts. That is the closest thing to a public figure on what the company hands back to hold usage.
Renewal timing is the lever. More than 11,900 accounts now spend above $100,000 a year, from about 400 in March 2025, and net revenue retention was approximately 900% at September 30, 2026. Committed spend is what buys a committed price list in this filing’s account of enterprise contracts, and the risk section says the growth may not hold.
The Neural Minute take
Our reading of the first filing ended on an open question. Trailing revenue per employee of $6.6 million implied close to $15 billion for the September quarter that the October 26 document never reported. The amendment reports $16,956 million, so the arithmetic holds and the gap was a missing table, not a missing business.
The rest is a company that changed shape in nine months. Revenue went from $376 million in the first quarter of 2025 to $16,956 million in the third quarter of 2026. No other lab publishes a series anything like it, and none of these lines would have been readable a year ago.
Two readings are wrong. The $23.3 billion loss is not a cash problem, since $21.9 billion of it is a mark that converts or reverses at listing. But $17 billion of quarterly revenue is not proof of a durable business either, with $895.4 billion of compute already contracted, a tenth of it due within a year, and an operating loss still on the page.
What the filing does establish is the price of capacity bought late. The June quarter’s 48% was the good case, when committed compute arrived against rising revenue. September’s 58% is the other case. $69.8 billion of committed compute spend falls due inside the twelve months after September 30. For anyone paying for tokens, that is the number that decides how generous the next price list can be, and how likely the next rate limit is.
Sources
- Anthropic, PBC, Amendment No. 1 to Form S-1, filed November 2, 2026: filing on sec.gov
- Our reading of the first S-1, October 27, 2026: Anthropic files for IPO with $16.3 billion in six months
- Our coverage of Claude Haiku 5.5 pricing, October 2026: Anthropic prices Haiku 5.5 at $0.10 per million tokens